

Original market intelligence, analysed, cross-referenced and published by Blockbeat News.
Binance hack prompts Aave lending freeze across 16 networks
Aave’s reported suspension of lending across 16 networks turned the roughly $6 billion Binance theft into a DeFi market-access event. The response shows how external asset provenance, redemption constraints and emergency controls can override normal protocol economics without any reported failure in Aave’s contracts.
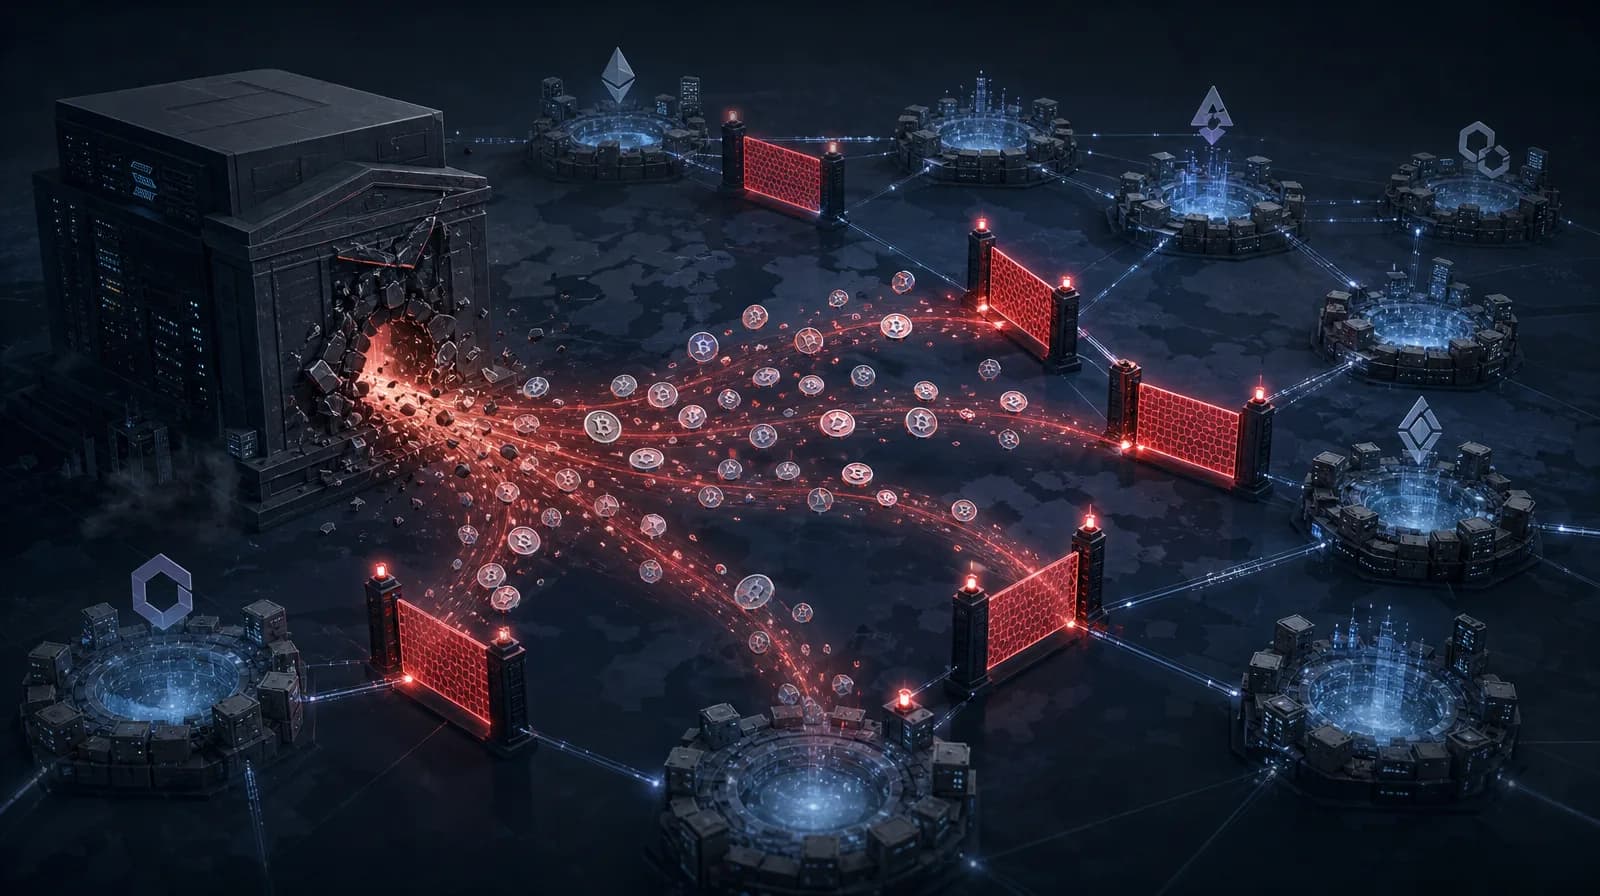
Aave reportedly suspended lending across 16 networks on 30 October after assets stolen from Binance began moving through decentralised finance. DeFi exchanges also halted trading in affected markets, while the FBI attributed the roughly $6 billion theft to North Korea and asked market participants to block identified Bitcoin, Ethereum and Solana addresses.
The breach originated at a centralised exchange, but its operational consequences spread into lending markets and decentralised trading venues. Aave was not reported to have suffered a contract failure. Its intervention was instead a response to external assets entering systems that ordinarily execute according to collateral rules, prices and available liquidity rather than the provenance of funds.
That distinction is the strongest new evidence since routing and revenue allocation dominated the previous DeFi assessment. Route control is now being used defensively: protocols and interfaces that compete to attract transactions have also demonstrated that they can restrict markets when a sufficiently large security and legal risk arrives.
A venue breach became a lending-market event
The preceding 30 days included a reported $387.5 million Bitget breach and the return of $3.8 million stolen from NEAR Intents. Those responses remained more closely associated with the affected services and recovery of particular assets. Binance’s larger loss, followed by movements through multiple chains and DeFi venues, made the acceptability of incoming liquidity a wider market concern.
Pausing lending can prevent a market from accepting fresh credit exposure while an incident is assessed. It does not recover stolen assets, establish legal ownership or stop their movement through every alternative venue. The scope also depends on how the pause was implemented. A restriction at a hosted interface can block ordinary access while leaving an underlying contract callable through another route; a contract-level pause can disable specified functions more directly.
Public reporting did not establish that every Aave deployment, interface and market was restricted in exactly the same way. The reported reach across 16 networks is nevertheless material. A common emergency decision affected users and liquidity pools well beyond Binance, showing that a multi-chain protocol can distribute normal activity broadly while retaining controls capable of producing a similarly broad interruption.
The timing sharpened that point. On 28 October, Aave raised Bitcoin and Ether collateral borrowing limits across V3 and V4. Two days later, it reportedly froze lending across 16 networks. The higher limits were not reported to have caused the suspension, but the sequence demonstrates how quickly an expansionary risk decision can be overtaken by an external event.
The FBI request depends on enforceable access points
The FBI’s request to block specified addresses was not self-executing. Its effect depends on which organisations can identify the assets, which components they control and whether those components can refuse transactions.
Custodians and hosted interfaces can screen users or addresses. Protocol administrators may be able to pause markets or change parameters. An automated market maker without equivalent controls may continue to execute if a user can call its contracts directly. Bridges and other routing services add further decision points as assets move between networks.
This produces an uneven response rather than a single DeFi-wide block. Some routes can close quickly, while others may remain available until governance, administrators or service providers act. The Binance incident therefore exposed a practical dependency on off-chain intelligence and discretionary intervention: protocols needed address attribution from investigators before deciding which activity to restrict.
Stolen flow can raise reported protocol revenue
An investigator subsequently linked movements of the stolen Binance assets to higher revenue at DeFi protocols. No aggregate figure was supplied, and the report did not suggest that the venues knowingly solicited the activity.
The mechanism is straightforward. Automated pools and routing services can charge fees whenever assets are swapped or transferred through them, irrespective of whether the beneficial owner is a normal trader or an alleged attacker. A sufficiently large laundering or asset-conversion flow can therefore increase recorded fees even while venues are attempting to stop it.
This weakens the value of revenue as a standalone measure of market health. Fee growth generated by an emergency does not demonstrate durable user demand, improved liquidity-provider returns or a safer lending environment. It may instead record the cost paid by an attacker to obtain different assets or reach another exit route. Protocols will also need to determine whether any identifiable fees associated with blocked assets can be retained, segregated or recovered.
Oracle coverage cannot guarantee redemption liquidity
A separate Bitcoin redemption freeze placed a reported $136 million Aave market under scrutiny on 1 November. There was no reported connection to the Binance theft, but the event exposed another external dependency in DeFi lending.
A price feed can continue to value collateral even when its redemption mechanism is unavailable. If a wrapped or tokenised asset cannot be redeemed for the underlying asset, arbitrage becomes harder and lenders depend more heavily on secondary-market liquidity. Liquidation parameters based on an observable price may offer incomplete protection when the asset cannot be converted through its normal exit route.
Aave Horizon addressed a related pricing problem during the same week by adopting Chainlink data derived from perpetual futures for tokenised stock collateral at weekends. The service extends price coverage while conventional equity markets are closed. It does not make the underlying shares redeemable or ensure sufficient weekend liquidity to absorb a liquidation. Any divergence between the perpetual market and the next cash-market opening remains relevant to borrowers and lenders.
Aave’s reopening notices will provide the next observable test. The important details will be whether all 16 networks resume together, whether address restrictions remain after lending restarts, and how affected venues account for fees generated as the stolen assets passed through their markets.
Related reading
Intelligence ·
Uniswap routes rival liquidity while Aero directs seven-chain revenue to stakers
Uniswap’s addition of seven external trading sources and the Aerodrome-Velodrome merger extend DEX economics beyond isolated liquidity pools. The designs could improve execution and strengthen token value capture, but they leave liquidity providers, route security and chain-level fragmentation as material dependencies.
Intelligence ·
Binance’s $6.3 billion hack separates reserve backing from withdrawal access
Binance said it replaced 90% of the assets stolen in a $6.3 billion hot-wallet breach, using company resources and its user protection fund while withdrawals remained suspended. The response may prevent customer losses, but it leaves liquidity, operational access and the recovery of frozen assets as separate tests.
Intelligence ·
Aave and Morpho bring tokenised stocks into DeFi collateral markets
Tokenised securities and funds are shifting from standalone investment products into collateral, lending and yield markets. The change expands DeFi’s addressable asset base while importing new dependencies on custody, pricing, legal rights and offchain settlement.
Intelligence ·
Tokenised securities expand DeFi lending and collateral markets
Tokenised securities and funds are moving beyond issuance into lending, collateral and settlement. The shift positions DeFi as financial infrastructure, while making liquidity, redemption and risk assessment increasingly important.