

Original market intelligence, analysed, cross-referenced and published by Blockbeat News.
Uniswap routes rival liquidity while Aero directs seven-chain revenue to stakers
Uniswap’s addition of seven external trading sources and the Aerodrome-Velodrome merger extend DEX economics beyond isolated liquidity pools. The designs could improve execution and strengthen token value capture, but they leave liquidity providers, route security and chain-level fragmentation as material dependencies.
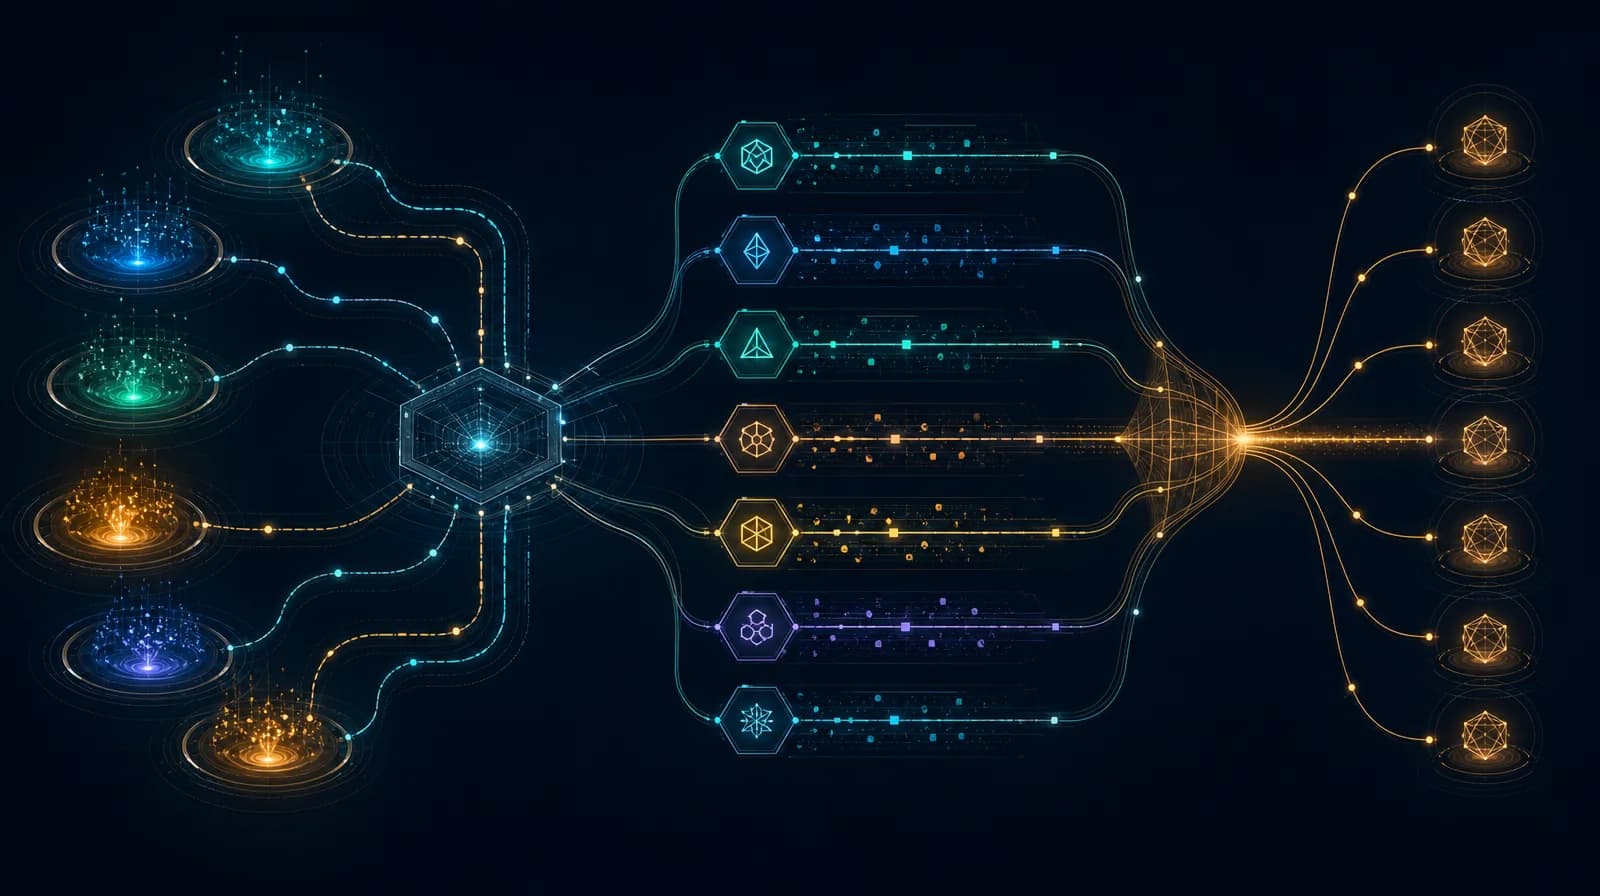
Uniswap has opened its routing system to seven external trading sources, allowing trades initiated through its product to be filled outside Uniswap’s own pools. The reported design directs fees from this external routing towards UNI burns, giving the protocol an economic claim on trades for which another venue supplies the liquidity.
Aero has taken a different route to the same commercial objective. Formed through the merger of Aerodrome and Velodrome, it combines exchange activity across seven chains and directs all exchange revenue to AERO stakers. One model aggregates rival venues; the other unifies related venues under one token and revenue policy. Both seek to control the order path and fee allocation without requiring every trade to occur in a single pool or on a single network.
This is the strongest new development since extreme leverage dominated the previous DeFi assessment. It changes how decentralised exchanges can compete: pool depth remains important, but a protocol can retain the user relationship and some transaction economics even when execution occurs elsewhere.
Uniswap separates routing from pool ownership
A conventional automated market maker earns its position by attracting assets into its own pools. Traders pay liquidity-provider fees when those pools execute a swap, while the venue competes on price, slippage and available token pairs. An aggregator instead compares multiple sources and selects a route based on the resulting quote.
By incorporating seven external sources through its v4 routing design, Uniswap can present a broader set of prices without supplying all the underlying liquidity. If a rival venue offers better execution, the user can remain within Uniswap’s product while the trade is routed externally. The associated fee can still contribute to a UNI burn.
The allocation matters. A burn reduces token supply but does not provide UNI holders with a direct cash payment. Nor does it necessarily compensate a liquidity provider whose pool loses order flow to an external route. Uniswap’s token holders, interface users and pool depositors therefore have different interests: users benefit from better quotes, token holders may benefit from greater burns, and liquidity providers depend on their pools continuing to win trades.
Actual routing data will determine whether those interests remain aligned. If external venues capture a substantial share of execution, Uniswap could strengthen its position as an order gateway while weakening fee generation in some native pools. If its own liquidity continues to provide the best quotes, external routing may instead function mainly as protection against gaps in price or asset coverage.
Security also becomes a wider dependency. Programmable hooks can alter how swaps and fees behave, while external routing introduces contracts and liquidity sources beyond a single venue’s direct control. 0x has publicly disputed the adequacy of protections against malicious hooks; that disagreement does not establish an exploit, but it identifies route validation as an unresolved part of the design.
Aero combines revenue while liquidity stays chain-specific
Aero’s merger addresses fragmentation through common governance and economics rather than external aggregation. Aerodrome and Velodrome now operate under one system spanning seven networks, with exchange revenue assigned to AERO stakers.
The arrangement creates a clearer token-level claim on activity across the combined venues. It can also reduce duplicated incentive programmes and competing governance decisions between related exchanges. Revenue from several deployments can support one staking system instead of being divided between separate tokens and communities.
Liquidity nevertheless remains chain-specific. Assets deposited on one network cannot automatically quote or settle a trade on another, and each deployment retains its own users, transaction costs and smart-contract risks. A shared token can combine revenue accounting, branding and incentive policy, but it does not by itself create a single pool of executable liquidity across seven chains.
Aero will consequently need to demonstrate that the merger retains capital at the deployment level. Aggregate revenue could rise while liquidity becomes concentrated on one or two networks, leaving the remaining markets dependent on incentives. Chain-by-chain volume, fee income and liquidity retention will be more informative than a combined headline figure.
Balancer’s wind-down sets the economic baseline
The preceding 30 days supplied a warning about the alternative to aggregation and merger. Balancer considered closure after restructuring failed to restore revenue. During the current window, BAL holders approved the wind-down, rejected an official fork and set shutdown dates.
A subsequent review identified more than $500,000 in overlooked user assets. The discovery does not alter the governance decision, but it shows that closing a mature exchange involves residual claims and asset reconciliation after active operations have ceased.
Balancer’s outcome does not prove that broader routing or merged token economics will succeed. It does establish the commercial context in which Uniswap and Aero are acting. A decentralised exchange must generate sufficient value for liquidity providers, users and whichever constituency receives protocol fees; token issuance cannot indefinitely substitute for competitive execution and recurring revenue.
The next evidence should come from measurable allocation rather than launch announcements. Uniswap’s externally routed volume, native-pool execution and resulting UNI burns will show whether aggregation expands its economics or displaces its liquidity providers. Aero’s chain-level liquidity and staker payouts will indicate whether common revenue policy can hold together markets that remain operationally separate.
Related reading
Intelligence ·
Tokenised bonds and bank deposits move into operating financial products
Tokenised deposits, bonds, private assets and stablecoin payments are moving into operational financial products. Adoption is splitting between institutionally controlled settlement infrastructure and consumer-facing stablecoin services, while security and liquidity risks remain unresolved.
Intelligence ·
Tokenised securities expand DeFi lending and collateral markets
Tokenised securities and funds are moving beyond issuance into lending, collateral and settlement. The shift positions DeFi as financial infrastructure, while making liquidity, redemption and risk assessment increasingly important.
Intelligence ·
Papertrade losses expose the risks behind leveraged DeFi volume
New 1,000x perpetual products generated substantial notional activity, but Papertrade’s reported $32.4 million of trader losses and subsequent controls show why volume is a weak proxy for durable demand. Evidence from Uniswap liquidity providers and PancakeSwap’s proposed economic overhaul points to a broader focus on net returns rather than headline activity.
Intelligence ·
Morpho and Kraken expand borrowing against tokenised stocks
In the 30 days to 22 September, tokenised equities, funds and other real-world assets moved beyond issuance into borrowing, yield and collateral products. The shift deepens institutional use of DeFi infrastructure, but stressed redemptions and high-LTV lending show that onchain distribution does not remove underlying credit, liquidity or governance risk.