

Tokenised assets move from issuance to DeFi collateral
Tokenised securities and funds are shifting from standalone investment products into collateral, lending and yield markets. The change expands DeFi’s addressable asset base while importing new dependencies on custody, pricing, legal rights and offchain settlement.
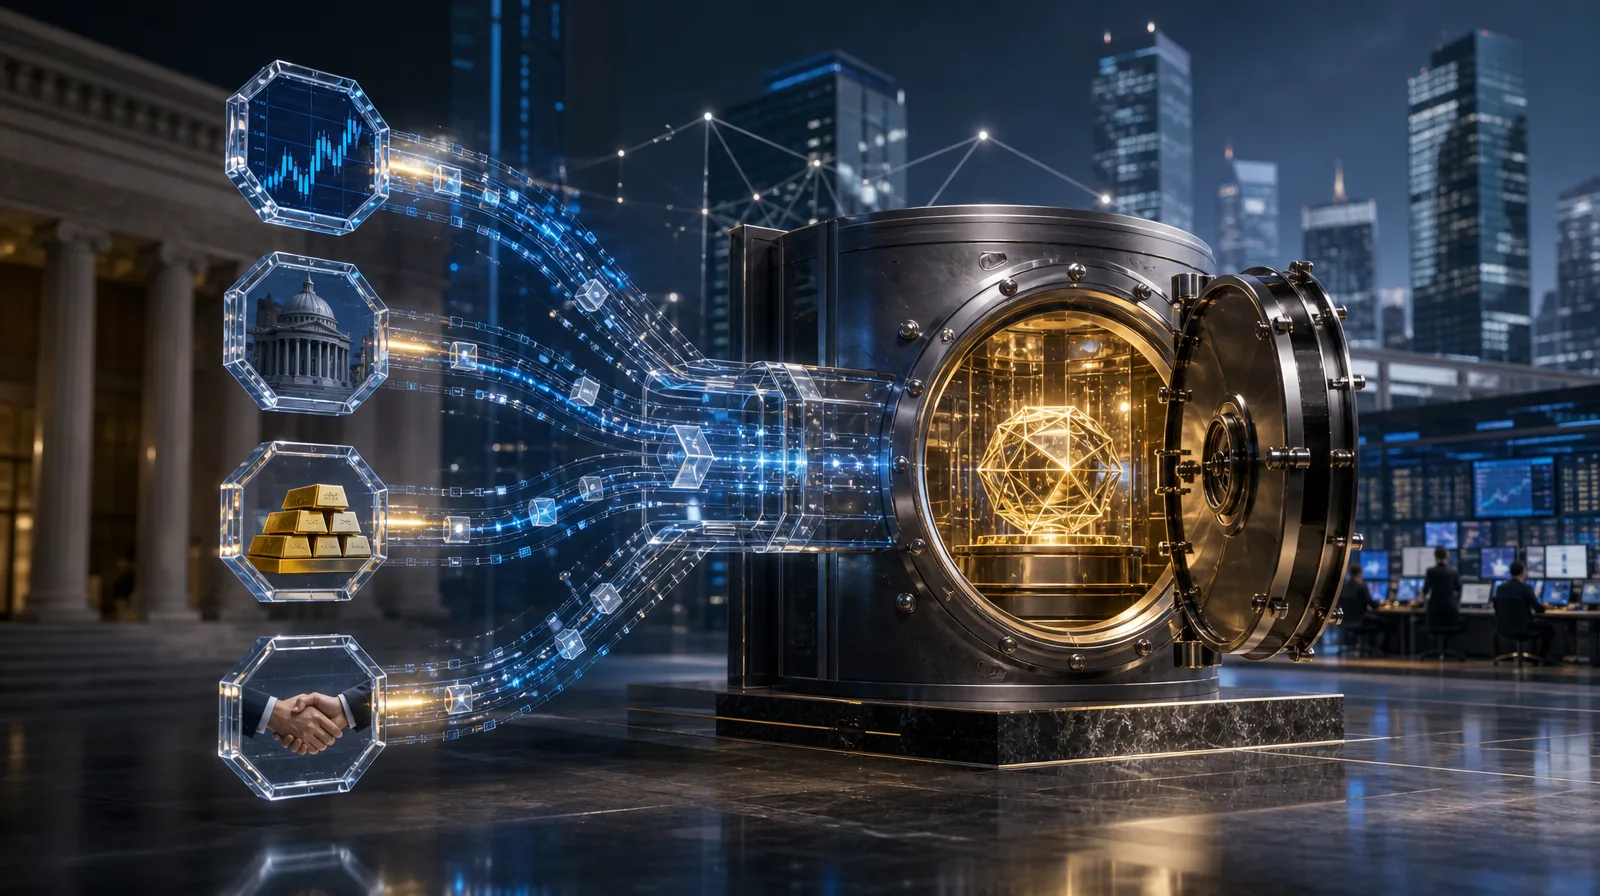
Across the current 30-day snapshot, the clearest structural change in decentralised finance is the movement of tokenised real-world assets into DeFi’s credit machinery. The sector is no longer focused primarily on putting conventional assets onchain; protocols and trading venues are increasingly using those assets as collateral, liquidity sources and yield-bearing balance-sheet instruments.
The preceding period established the direction through large fund integrations and forecasts for tokenised real-world assets. The latest phase is more operational. Aave added Coinbase stock tokens as collateral on Base and outlined a separate credit market for tokenised assets on Avalanche. Morpho introduced borrowing against Coinbase’s tokenised stocks, while Kraken launched vaults for borrowing against tokenised equities and offered DeFi yield on tokenised stocks and exchange-traded funds.
This is a material broadening of DeFi’s collateral base. Historically, onchain lending has depended heavily on crypto-native assets and stablecoins whose values remain closely connected to digital-asset market conditions. Tokenised equities, funds, gold and private credit introduce claims linked to different cash flows and market cycles. In principle, that can improve capital efficiency and diversification. In practice, it also makes DeFi more dependent on the legal and operational systems supporting each token.
From wrappers to financial building blocks
Product development during the period points towards greater composability. Ondo introduced in-kind minting for tokenised US stocks, allowing conventional shares to be exchanged for digital representations, and added spot trading for tokenised stocks and ETFs. Paxos Labs launched a product designed to generate lending yield from tokenised gold. Franklin Templeton fund shares became eligible collateral on Bybit, while Kamino opened a Solana collateral market linked to GPU loans.
These launches indicate that tokenisation is moving beyond passive ownership. The emerging model combines an offchain asset, an onchain representation and a credit or trading layer built around it. That structure can support borrowing, leveraged trading and automated portfolio management without requiring the underlying security to move continuously between traditional intermediaries.
Distribution is widening alongside functionality. Reported ownership of tokenised stocks reached 4.3 million holders, led by activity on BNB Chain. However, holder numbers do not by themselves establish market depth: economic exposure may remain concentrated, while liquidity can fragment across chains, issuers and trading venues.
Institutional rails are closing the loop
The build-out is increasingly connected to established financial infrastructure. Ondo’s broker-dealer platform joined DTCC’s Fund/SERV network, and Blockchain.com and the New York Stock Exchange began exploring round-the-clock tokenised stock trading. Six Canadian banks launched an initial tokenised-deposit initiative, while IBM linked its digital-asset infrastructure to a SWIFT ledger in beta testing.
Stablecoins remain the likely settlement bridge. Cross-border stablecoin flows rose by 77.5%, although activity remained concentrated in a limited number of markets. Citi’s reported work with Coinbase on corporate stablecoin payments, Mastercard-owned BVNK’s adoption of Stellar rails and Circle’s launch of Arc with participation from BlackRock, DTCC and Visa all reinforce the convergence between tokenised assets, programmable settlement and institutional distribution.
The implication for DeFi is that growth may increasingly come from providing financial functions around externally originated assets rather than creating wholly crypto-native ones. Lending protocols, decentralised exchanges and vault managers can become the execution layer for assets issued or administered elsewhere.
Composability also expands the risk perimeter
The same architecture introduces dependencies that smart contracts cannot eliminate. Tokenised securities rely on custodians, transfer agents, issuers and enforceable ownership rights. Their trading hours and redemption terms may differ from the continuous operation of DeFi markets. Oracle failures or stale prices can therefore become more consequential when assets are used as leveraged collateral.
Recent stress events underline that risk. AlphaFi wound down after an oracle error, while Neutrl began redeeming NUSD at 51 cents amid difficulties affecting an underlying junior tranche. A reported yield shortfall in tokenised money-market funds also showed that an onchain wrapper does not remove the economics of the underlying product. Separately, debate over Morpho’s curator model and Aave’s classification of vaults highlighted the importance of determining where responsibility sits in increasingly modular lending markets.
The next test is consequently not issuance volume but collateral performance. Sustainable adoption will depend on whether tokenised assets can retain reliable pricing, redemption and legal enforceability during periods when traditional markets are closed or onchain leverage is unwinding. DeFi is gaining access to a larger financial universe, but it is also inheriting that universe’s operational constraints.