

Original market intelligence, analysed, cross-referenced and published by Blockbeat News.
DTCC launches 34 securities while 33 companies challenge OKX-ICE tokenisation
DTCC has activated a tokenised securities service for 20 clients, while 33 companies have objected to an OKX-ICE proposal covering their shares. The competing developments show that control over ownership records and investor rights is becoming decisive in blockchain deployment.
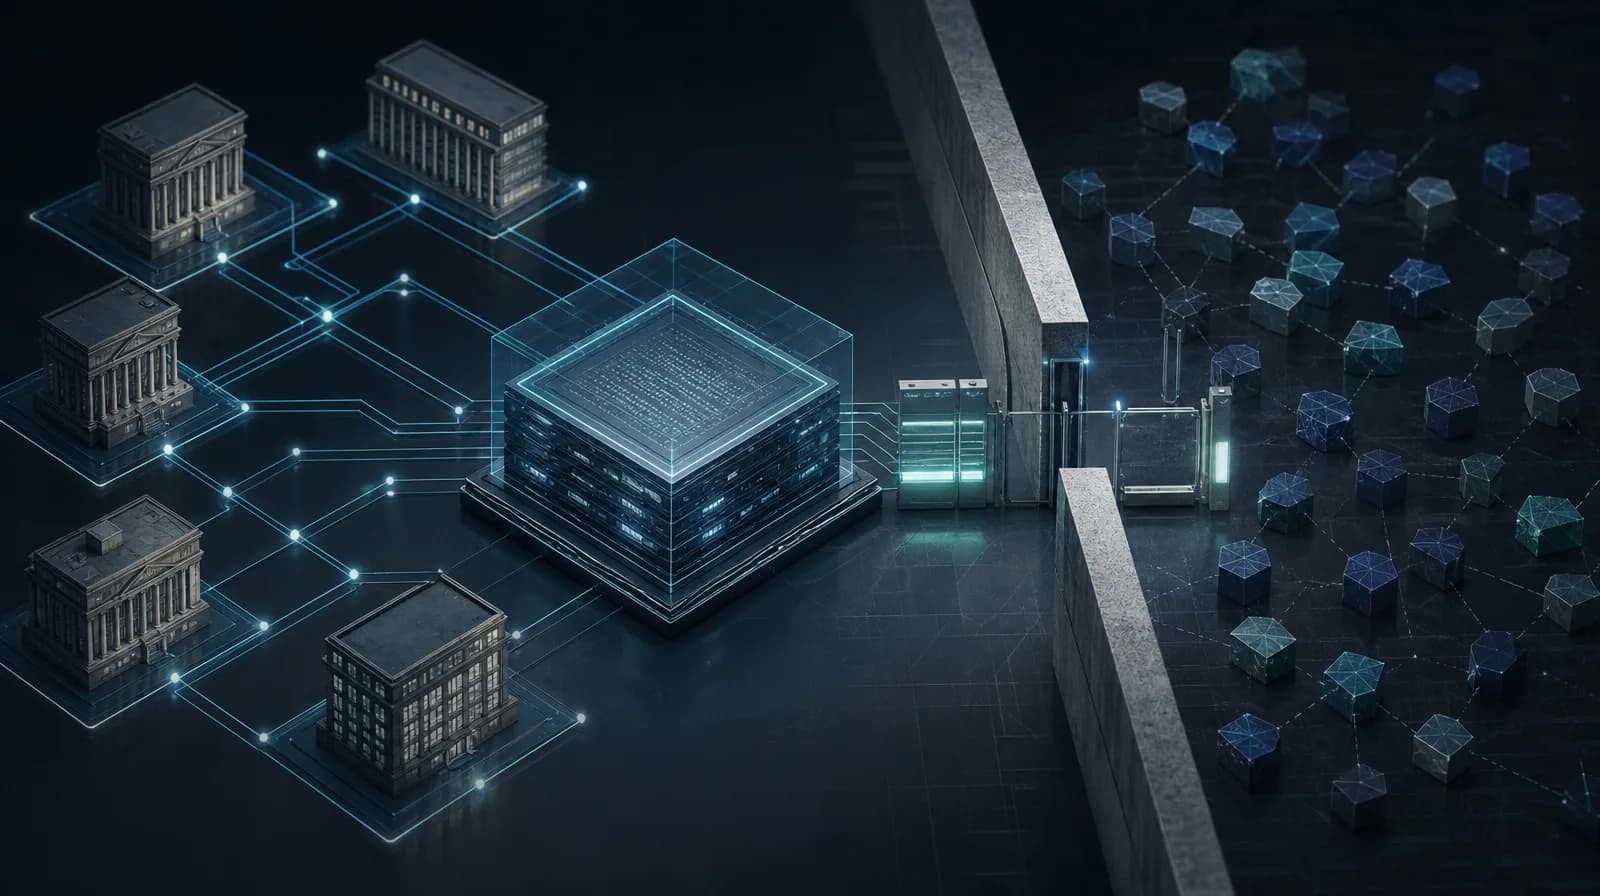
The Depository Trust & Clearing Corporation activated its tokenised securities service for 20 clients by 28 October, with 34 securities reportedly available at launch. The deployment exceeded an earlier plan for 25 securities and brought an October launch commitment into operation.
DTCC’s position makes the event more consequential than another fund manager issuing assets on a public blockchain. It operates core US post-trade systems and services securities reported to be worth about $30 trillion. That figure describes the existing market within DTCC’s reach, rather than the value tokenised at launch, but it gives the organisation a direct connection to the records, participants and controls needed to make digital representations usable in established markets.
A parallel development exposed the limits of tokenisation undertaken without the same relationship to issuers. Thirty-three companies, including JPMorgan, Coca-Cola, Adobe, Dell, Intel, Oracle and IBM, objected to an OKX-Intercontinental Exchange proposal for tokenised trading in 63 US stocks. Their reported concerns covered regulatory compliance, market integrity, operations and the use of corporate brands.
Together, the events establish a practical divide in securities deployment. A blockchain can record and transfer tokens, but the commercial value of those tokens depends on who controls the recognised ownership record, administers corporate actions and provides redemption or conversion into the underlying security.
DTCC brings tokenisation closer to the official record
DTCC’s initial cohort remains small relative to its wider business: 20 clients and 34 securities do not demonstrate migration across a $30 trillion market. They do, however, move tokenisation into an operating service managed by an organisation already responsible for central securities processing.
That position can reduce a persistent source of ambiguity. When a token is issued separately from an existing security, investors need to know whether it represents direct ownership, an entitlement held through a custodian or a contractual claim against an intermediary. Dividends, voting rights, stock splits, transfer restrictions and insolvency treatment all depend on that legal and operational design. A market utility can connect the tokenisation process more directly to participant records and established controls, even where the token does not replace every conventional system involved in settlement.
The announced use of Canton and Besu also makes exclusivity to one blockchain less important than compatibility with participating institutions. Supporting two ledger environments may widen access, but it creates a requirement to keep asset identities, transaction states and permissions consistent wherever the same security can be represented. The launch therefore tests operational coordination as much as ledger performance.
Evidence of sustained transfers, settlement and corporate-action processing will matter more than the nominal value of securities accessible through DTCC. Until that activity is visible, the service should be treated as a bounded production launch rather than evidence that the depository’s full asset base has moved onchain.
Corporate objections expose the wrapper problem
OKX and Intercontinental Exchange sought approval earlier in October for round-the-clock trading in 63 tokenised stocks. The number of objecting companies subsequently rose from an initial group to 33 by 28 October, potentially affecting more than half the proposed selection.
Issuer opposition does not automatically prevent an intermediary from creating a product linked to publicly traded shares. Its impact depends on the product’s legal design and the approval process governing the venue. It nevertheless raises a commercial and technical problem that network capacity cannot resolve.
A third-party token can track a share price or pass through economic rights while the underlying stock remains with a custodian. Investors then rely on the intermediary to process dividends, voting instructions and other corporate actions correctly. Trading hours can also diverge: a token may change hands while the primary equity market is closed, leaving the venue dependent on its own liquidity and price formation until the underlying market reopens.
The objections indicate that access to market prices and custody of underlying shares may not be sufficient to secure issuer acceptance. The involvement of ICE, which owns the New York Stock Exchange, gives the proposal substantial market experience but does not remove questions about whether companies consent to the use of their names and securities in a separate tokenised venue.
Asset managers retain control over fund tokens
Recent fund deployments follow a more controlled route. Aviva Investors tokenised a £50 million share class of its roughly £22 billion Sterling Liquidity Fund on the XRP Ledger. Franklin Templeton added $150 million of fund shares to the same network, although the reported amount was concentrated in one wallet and therefore does not establish broad investor distribution. JPMorgan brought tokenised money-market funds to Solana, while Securitize added Stellar to its supported networks.
These projects distribute institutional assets across XRP Ledger, Solana, Stellar, Canton and Besu rather than concentrating them on one chain. Their common feature is the participation of the asset manager, administrator or market utility responsible for the product. That allows transfer rules, investor eligibility and redemption processes to be incorporated at issuance instead of reconstructed by a separate venue after the fact.
The chain still affects transaction costs, availability, privacy and integration. It does not determine the legal claim represented by the token. The current deployments suggest that financial institutions are selecting networks for particular products while retaining control over asset administration and investor access.
The next observable tests are whether DTCC’s 20-client service records sustained transactions and corporate actions beyond its launch cohort, and whether OKX-ICE reduces or redesigns its proposed 63-stock offering after the issuer objections. Those developments will define the practical boundary between authorised digital ownership records and externally created securities wrappers.
Related reading
Intelligence ·
Hana Bank’s blockchain bond advances tokenised debt settlement
Over the past 30 days, institutional blockchain activity has broadened from experimental asset issuance into settlement, deposits and purpose-built transaction infrastructure. The shift remains uneven, but live bond deals and always-on payment initiatives indicate that tokenisation is becoming more closely integrated with conventional finance.
Intelligence ·
Tokenised bonds and bank deposits move into operating financial products
Tokenised deposits, bonds, private assets and stablecoin payments are moving into operational financial products. Adoption is splitting between institutionally controlled settlement infrastructure and consumer-facing stablecoin services, while security and liquidity risks remain unresolved.
Intelligence ·
Polygon licences and Samsung Wallet plans widen stablecoin distribution
Stablecoins and tokenised assets are moving beyond blockchain-native venues into licensed payment networks, mobile wallets and institutional products. The emerging competitive advantage is distribution and regulatory access, although security and asset integrity remain material constraints.
Intelligence ·
Smaller blockchains consider migration as institutions expand settlement networks
Smaller layer-one networks are considering or approving migrations to larger ecosystems as institutions deploy blockchain for bonds, stablecoins and settlement. The pattern points towards consolidation at the base layer alongside greater specialisation in financial applications.