

DeFi’s Institutional Phase Is Becoming Infrastructure, Not Experimentation
Stablecoins, tokenised assets, institutional lending and blockchain settlement are beginning to converge with traditional finance, suggesting DeFi's next phase could be far less visible than its first.
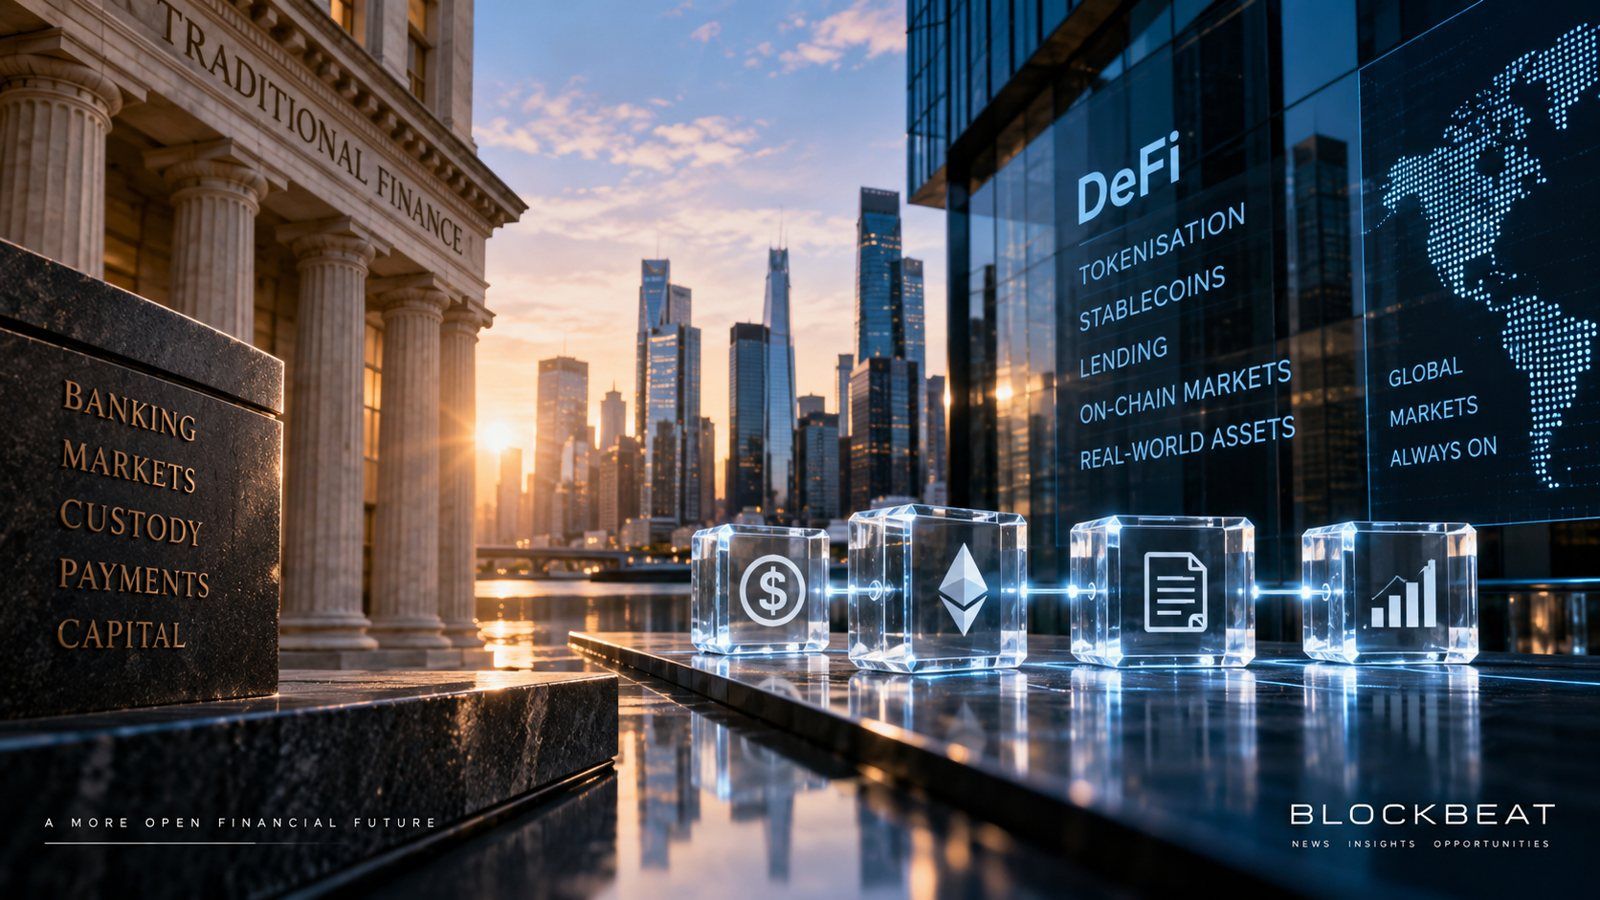
The most significant DeFi development this week was not a single protocol launch, investment or market event. It was the increasingly visible convergence between decentralised finance and the infrastructure of traditional financial markets.
Stablecoins moved deeper into banking and payments. Tokenised securities pushed further into conventional investment markets. Institutional lending expanded on-chain. Traditional financial institutions increased their exposure to blockchain-based infrastructure.
Individually, these developments could be viewed as incremental. Together, they point towards a more substantial transition.
DeFi's institutional phase is beginning to look less like experimentation and increasingly like financial infrastructure.
Stablecoins are moving deeper into banking
One of the clearest signals came from U.S. Bank, which launched USBDC, its own dollar-backed stablecoin, and completed a live cross-border transaction using the Stellar network.
The significance is not simply the arrival of another stablecoin. A regulated financial institution is incorporating blockchain settlement into existing banking infrastructure while retaining conventional compliance, risk and operational controls.
That distinction matters.
For much of crypto's history, the industry attempted to construct financial infrastructure parallel to the banking system. Increasingly, banks and payment companies appear willing to adopt parts of that infrastructure themselves.
MoneyGram also launched a stablecoin-linked Visa card in Colombia, while payments infrastructure company Latitude secured $35 million to expand local stablecoin off-ramps.
Different products are addressing different parts of the financial system, but the underlying direction is similar. Stablecoins are moving beyond their role as crypto-native trading assets and becoming increasingly relevant to payments, settlement and the movement of money between conventional and blockchain-based systems.
Tokenisation is becoming a market structure question
Tokenised securities provided another strong signal.
Nasdaq announced a $100 million investment in Payward, the parent company of Kraken, as part of a wider relationship involving tokenised equities and markets capable of operating beyond conventional exchange hours.
ARK Invest separately sought regulatory approval for a tokenised share class of one of its venture funds, while Valinor launched a tokenised business development company fund through Superstate.
Tokenised stocks also reportedly generated around $1 billion in trading while conventional US equity markets were closed.
The important question is therefore shifting.
It is becoming less about whether conventional assets can be tokenised and more about what happens to financial markets if meaningful volumes of those assets begin trading on infrastructure that does not share the restrictions of traditional exchanges.
Conventional securities markets remain constrained by trading hours, settlement processes, intermediaries and geographic boundaries. Blockchain-based markets can potentially operate continuously.
That does not mean conventional exchanges are about to disappear. It does mean that some of the assumptions underpinning their existing market structure are beginning to face credible technological competition.
DeFi lending is changing shape
The lending market is evolving as well.
Compound introduced an institutional-only lending market, while Morpho expanded its fixed-rate lending products on Ethereum. Tether and Fasanara also established a $400 million private credit fund.
This increasingly resembles a different generation of decentralised finance.
Early DeFi lending was dominated by crypto-native borrowers, over-collateralised positions and highly variable interest rates. Institutional participation requires something different: predictable pricing, controlled access, credible counterparties, compliant infrastructure and assets that extend beyond cryptocurrencies themselves.
Fixed rates, institutional markets, tokenised real-world assets and private credit bring DeFi much closer to products already familiar within traditional finance.
The distinction between a "DeFi product" and a "financial product using decentralised infrastructure" may consequently become increasingly difficult to maintain.
The convergence is happening in both directions
It would be easy to interpret institutional adoption as traditional finance gradually absorbing crypto.
That misses half of what is happening.
Uniswap's introduction of dynamic fees for stable-pair liquidity pools is an example of financial infrastructure evolving from within decentralised markets themselves. Rather than simply reproducing an existing banking product on a blockchain, decentralised markets continue to develop mechanisms that conventional finance did not originate.
The result is movement in both directions.
Banks are adopting blockchain settlement and stablecoins. Exchanges and asset managers are exploring tokenisation. Meanwhile, DeFi protocols are introducing institutional markets, fixed-rate products and increasingly sophisticated liquidity mechanisms.
What appears to be emerging is neither traditional finance replacing DeFi nor DeFi replacing traditional finance.
It is a financial architecture borrowing increasingly heavily from both.
Infrastructure remains the weakness
The transition is far from complete.
Blockchain infrastructure continues to present technical, governance and security risks that regulated financial institutions will be reluctant to inherit.
Disruption affecting Robinhood Chain's use of Ethereum blob capacity illustrated the dependencies that can emerge between different blockchain layers. Router Protocol's planned shutdown demonstrated another reality of decentralised markets: infrastructure that appears established can disappear.
Governance disputes and security incidents provide further reminders that decentralised infrastructure introduces risks that conventional financial systems have spent decades building processes to contain.
Regulation presents another constraint.
Tokenised equities raise unresolved questions around issuer consent, investor protection, securities law and the legal relationship between an underlying asset and its blockchain representation.
The technology may be advancing faster than the regulatory architecture surrounding it.
That gap could become one of the defining tensions of the next phase.
DeFi may disappear into finance
The strongest signal from the week is not that DeFi has suddenly achieved institutional adoption.
It is that the dividing line between decentralised finance and conventional financial infrastructure is becoming less useful.
Banks are experimenting with stablecoins. Exchanges are exploring tokenisation. Asset managers are seeking tokenised investment products. DeFi protocols are developing institutional lending markets. Payment companies are connecting stablecoins to conventional card networks.
If those developments continue, the next phase of DeFi could look very different from the one that created the sector.
Consumers may use a bank, brokerage account, payment card or investment product without knowing that blockchain infrastructure is operating somewhere underneath it.
That would represent a profound change in how adoption itself is measured.
The first phase of DeFi asked users to leave traditional finance and enter an alternative financial system.
The next phase may do precisely the opposite.
It may bring decentralised infrastructure into the financial products people already use.
If that happens, the long-term success of DeFi will not necessarily be measured by how many people describe themselves as DeFi users.
It may be measured by how many eventually use its infrastructure without realising they are doing so.
---
Blockbeat Intelligence examines developments across digital assets, blockchain and financial markets to identify emerging trends, structural changes and signals that may shape what happens next. The analysis represents independent editorial commentary and should not be interpreted as investment advice.